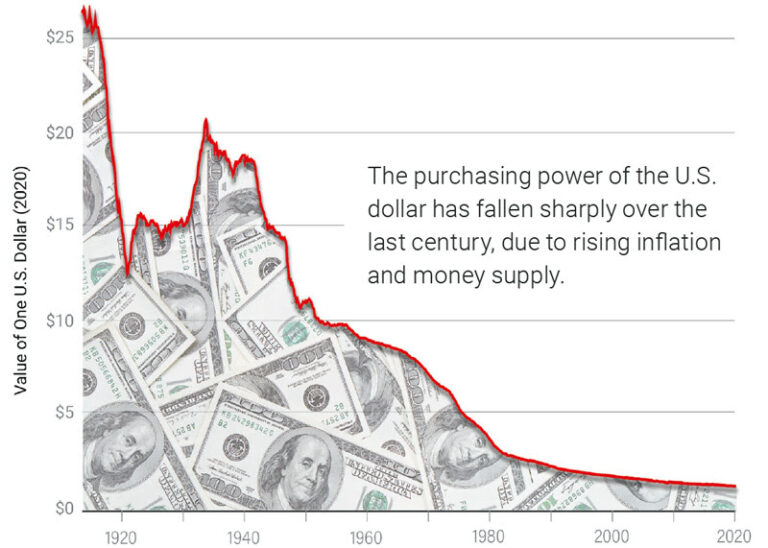
| The U.S. government’s own rigged CPI statistic says the dollar has lost 88% of its value since 1971.
Gold tells a harsher story: the dollar has lost over 99% of its value since 1971.
But the problem began before 1971.
Before 1971, the Bretton Woods system offered a partial gold standard. Foreign central banks could exchange dollars for gold at $35 per ounce. Average citizens could not.
The root of the problem reaches back to 1913.
That year marked a disaster for America and human freedom.
Congress passed the Federal Reserve Act, creating the country’s third central bank. The 16th Amendment also gave the federal government the power to levy an income tax.
These developments may seem unrelated. But what are the odds that the United States would adopt a central bank and an income tax in the same year?
Chance cannot explain the timing.
A closer look reveals how the Federal Reserve system depends on the income tax to function in its present form.
The structure works like this:
1. Central banks create fake money out of thin air.
2. They use this money to purchase government bonds and finance government borrowing.
3. Government debt forms the largest asset on the Fed’s balance sheet. What supports that debt? The government’s power to tax its citizens.
4. Governments use threats of imprisonment to extract taxes from average citizens to pay the interest and service the debt owed to the central bank, which created the money it loaned to the government out of thin air.
The federal income tax arrived months before Congress created the Federal Reserve in 1913. The connection matters.
What is the main asset central banks own?
Government bonds.
What supports the value of government bonds?
The government’s power to extract taxes from its citizens.
The income tax gives the U.S. government access to a vast funding source—a permanent, uncapped claim on the productivity of every citizen. Without it, the government would command a smaller funding base, its debt would attract less demand, and the central banking scam could not operate in its present form.
In short, you and your productivity serve as collateral for your government’s debts. Your labor supports the government bonds that sit on the central bank’s balance sheet—bonds the Fed purchases with money it creates from nothing.
That is the unvarnished truth about central banking.
In 1913, federal law fixed gold at $20.67 per ounce, and average citizens could exchange paper dollars for gold at that rate.
Even better, many citizens held physical gold coins instead of paper claims.
Gold served as money that ordinary Americans could own, save, and spend. The $20 Double Eagle contained 0.9675 ounces of gold, the $10 Eagle contained 0.48375 ounces, the $5 Half Eagle contained 0.24188 ounces, and the $2.50 Quarter Eagle contained 0.12094 ounces. Citizens used the smaller coins in commerce, while the larger denominations served as savings or payment for major purchases.
The creation of the Fed set the monetary system on a different course.
From 1913 to the present, the estimated U.S. broad money supply has expanded close to 1,500-fold.
The government’s rigged CPI statistics say the dollar has lost over 97% of its value since 1913.
Measured in gold, the US dollar has lost 99.5% of its value.
The dollar’s decline since 1913 echoes the fate of Rome’s denarius. Between AD 180 and 280, Rome stripped all but a trace of the silver from its currency as the empire descended into terminal decline.
That is the problem in a nutshell.
The fiat currency system has entered terminal decline. Currency debasement has accelerated, yet governments force everyone to use their failing money.
This 113-year-old trend predates every person alive. Its age hides it from view. Most people accept it as part of the natural environment, like a fish in water.
I suspect that illusion will soon shatter. The 113-year currency-debasement trend will shift into overdrive.
The next wave of currency debasement could destroy savings that took decades to build. Protecting that wealth—and the independence it gives you—starts with a plan. Choose wisely.
* Doug Casey’s International Man accurately predicted the massive rise in gold and the investment climate surrounding the 1980 gold bull market, primarily through his 1979 best-selling book- “Crisis Investing.” The book was the top-selling financial book of 1980, selling nearly half a million copies & spending 29 consecutive weeks at #1 on The New York Times bestseller list. Casey now sees gold rising to $10,000/ oz and advises against holding large amounts of fiat currency & recommends holding physical gold & silver to safely build wealth.
 The time tested asset that protects savings against asset bubbles and dollar devaluation, is physical gold & silver…Unlike a currency, gold can’t be hyperinflated away. Unlike a bond it cannot default. And unlike a company (stock) it cannot go bankrupt. It’s value cannot be debased by governments, who print paper money at will, making their currencies worth less every year.
Wise investors have been diversifying with gold & silver for centuries, to limit their exposure to poorly executed monetary and fiscal polices. And provide essential protection against: Asset bubbles, stock market declines, bank failures, global unrest & currency debasement. (inflation)
Physical gold & silver represent a safer, sounder store of value than debt & risk instruments denominated in fiat currency. Never forget, anything denominated in dollars (stocks, bonds, mutual funds, CD’s, annuities) lose purchasing power every day. While gold has maintained it’s value over time, better than any asset on earth. That makes it the best place to store your wealth.
As inflation makes our dollars worth less every day, more Americans are protecting their savings with physical gold & silver. A money that has no default risk and cannot be inflated away. Gold offers unparalleled profit potential, a proven track record of appreciation, privacy and wealth preservation.
Since 2008 the U.S. debt has exploded from $9 trillion to $40 trillion today. Hyperinflating the stock, bond and real estate markets & created the largest financial bubbles in history. And every Fed induced asset bubble has burst, every one…
“The U.S. stock market is in the largest bubble in history, and it will end in disaster. The risk of a major bear market is not a question of if, but when—and when it arrives, it will propel gold into the stratosphere & reach at least $15,000.” – Bubble Report
 Liberty Financial’s Guaranteed Gold Account is the #1 performing investment the last 25 years.
- 72% Average Annual Return (2000 – 2025)
- No Risk – 12 Month Buy Back.
- Always Liquid – Sell Anytime.
- IRA/401k Approved.
- Secured Physical Gold.
- Only $25K Minimum.
Don’t wait, call today (800) 723-8349. Or link below
https://www.libertyfinancial.org/72-certified-gold-account/
 Trusted Advice Since 1982
|